
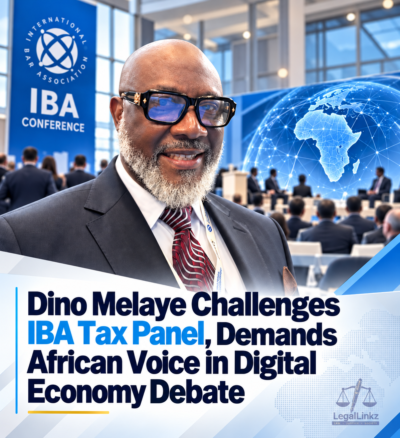
COPENHAGEN, DENMARK — Senator Dino Melaye, Esq., has challenged international tax experts at the ongoing International Bar Association Annual Conference 2026 to ensure that Africa is not treated as an afterthought in the global debate over taxation of the digital economy.
Melaye raised the issue during the IBA session “When Tech Triggers Tax,” held on Thursday, October 8, at the Bella Center in Copenhagen.
The session, organised by the IBA Taxes Committee, examined how new technologies and increasingly mobile workforces are reshaping international taxation, including questions around income tax, transfer pricing and withholding tax.
The panel was chaired by Alexandra Courela of Abreu Advogados, Lisbon, Portugal, and Francesco Gucciardo of Aird & Berlis, Toronto, Canada, with speakers drawn from Denmark, the United States, China, Italy and Chile.
Those jurisdictions became central to Melaye’s intervention.
After listening to comparative presentations from different parts of the world, he said the absence of an African perspective left an important gap in the discussion.
“Looking at the various jurisdictions, we’ve talked about Chile, Italy, Denmark, China, the US and, of course, Portugal. We’ve seen different perspectives to this,” Melaye said.
He continued:
“My only worry is that going forward, I really want to see an African on the panel to give us the African perspective of what is happening there.”
For Melaye, the issue was not simply representation for its own sake.
He argued that the international legal and tax community needs to understand whether digital economic services across African jurisdictions are developing, fully established or still structurally underdeveloped — because those realities will shape how global tax rules affect the continent.
“We need to know if digital economic services like this are evolving, or developed, or underdeveloped. We want to see the African perspective, so that we learn from there and then grow from there.”
The panel acknowledged the point, with the moderator indicating that the absence of an African voice would be taken into consideration in future conference planning.
That exchange, however, was only the beginning of Melaye’s intervention.
Having listened to the different national approaches presented by the panel, he said he had identified a significant mismatch in the way jurisdictions are responding to the taxation of technology and digital services.
“From the presentation from various jurisdictions, I’ve noticed some mismatch. There’s a lot of mismatch,” he said.
He then laid out four challenges which, in his view, require closer international attention.
The first was geographical fragmentation and trade wars.
Digital businesses can operate across several jurisdictions without a conventional physical presence, while governments increasingly pursue national tax measures designed to capture revenue from those activities.
That has created tension between jurisdictions over where digital value is created, where it should be taxed and whether unilateral digital taxes unfairly target companies headquartered elsewhere.
Those concerns are not theoretical. International tax policy has become increasingly entangled with trade policy, with governments using retaliatory measures where they believe foreign tax or digital rules discriminate against their companies.
In 2026, for instance, the United States used its Section 301 trade powers against Brazil over a package of measures that included digital trade and electronic-payment policies, demonstrating how regulatory disagreements in the digital economy can quickly escalate into wider trade disputes. United States Trade Representative
Melaye’s second concern went to the heart of digital-services taxation: the difference between taxing gross revenue and taxing net profit.
“Why conventional traditional taxes are levied on net profits, conversely most tech-specific digital taxes are levied on gross revenues,” he observed.
He then asked:
“How do you reconcile the disparity between tax from revenue and tax from profits, especially with digital services?”
That distinction is significant.
Traditional corporate income taxation is generally designed around profits after recognised costs and deductions.
Digital services taxes, by contrast, are often imposed on gross revenues generated from specified digital activities.
The OECD’s 2026 commentary on the international tax framework expressly notes that digital services taxes are generally calculated on gross revenue and are therefore ordinarily distinct from income taxes imposed on net income.
For technology companies with high revenues but differing margins across markets, the difference can materially affect the effective tax burden.
Melaye’s third concern was the corporate compliance burden created when multinational businesses must navigate overlapping and sometimes inconsistent tax regimes.
“The third is severe corporate compliance burden,” he said.
The problem becomes particularly acute where businesses operate simultaneously under domestic corporate tax systems, digital-services taxes, transfer-pricing rules, withholding-tax regimes and emerging international minimum-tax requirements.
The OECD continues to develop standardised reporting mechanisms under the Global Minimum Tax framework precisely because cross-border compliance has become one of the most technically demanding areas of modern multinational taxation.
Melaye’s fourth question concerned what he described as “the emerging AI and automation legal gaps.”
Artificial intelligence is changing how value is created, how services are delivered and even where economically significant activity is deemed to occur.
Automated systems can provide services in a country without a traditional office, large workforce or conventional physical business presence.
That challenges tax rules originally designed around geography, employees, physical assets and identifiable corporate operations.
Melaye asked the panel:
“How do we cure these challenges going forward?”
The panel described the issues he raised as substantial and worthy of deeper discussion.
Given the limited time remaining in the session, the moderator said addressing all four would effectively require another dedicated panel or future conference discussion.
Melaye accepted the response.
“Very well, very well. Thank you,” he replied.
The exchange captured the broader challenge behind the IBA session.
Technology is transforming commerce faster than traditional tax concepts can comfortably adapt.
The IBA itself framed “When Tech Triggers Tax” around precisely this problem: new technologies and highly mobile workforces are changing how goods and services reach consumers and how multinational groups organise resources across borders.
But Melaye’s intervention added another dimension.
The debate is not merely about updating tax rules.
It is also about who gets to participate in designing them.
Africa contains some of the world’s fastest-growing digital markets, a rapidly expanding population of technology users and governments increasingly interested in taxing value generated by global digital businesses.
Yet policies designed principally through the experiences of North America, Europe and parts of Asia may not automatically reflect African market structures, infrastructure, regulatory capacity or development priorities.
For Melaye, that is precisely why African lawyers, tax experts, regulators and policymakers must be present when international legal institutions discuss the future architecture of the digital economy.
His intervention therefore left the Copenhagen panel with two linked questions.
How should the world tax businesses whose economic activity no longer respects traditional borders?
And how credible can the resulting global framework be if an entire continent’s practical experience is insufficiently represented in the conversation?
At the IBA in Copenhagen, Melaye’s position was clear: Africa should not merely implement global digital-tax rules after they are developed elsewhere; Africa should help shape them.
Related Stories
READ MORE: Dino Melaye Presses IBA Panels on AI Ethics, Europe’s Ukraine Strategy Nigerian Law Updates
READ MORE: Ogunrinde: Dino Melaye’s IBA Intervention Projects Nigeria’s Voice on Rule of Law Nigerian Law Updates
READ MORE: IBA Copenhagen 2026 Opens With Nigerian Lawyers in Key Roles Nigerian Law Updates
behind Games Village, Abuja
5A, CGH, Games Village, Abuja